Understanding payment processing fees Canada how they work 2026 can make it easier to compare choices, prepare properly, and avoid common mistakes. This 2026 guide explains the practical details behind understand payment processing fees Canada, credit card fees Canadian merchant 2026, and interchange vs markup payment Canada, with straightforward points for beginners, owners, professionals, or consumers who want clearer information before taking action.
Interchange Is Only One Part of the Cost
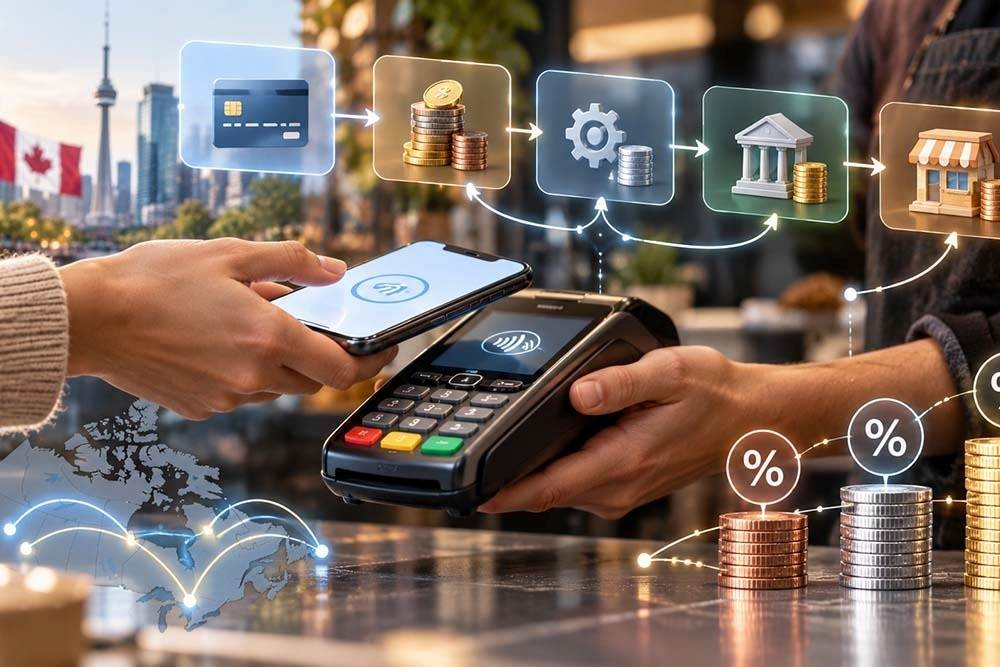
Payment processing pricing can look confusing because a merchant statement may combine network costs, interchange, processor markups, monthly charges and other service fees. Interchange is generally paid through the payment system to the card issuer and can vary by card type, transaction method and other characteristics of the payment.
How Processor Markups Are Added
Card-network assessments and processor charges may be separate from interchange. Merchants should avoid assuming that every line on a statement is controlled by the processor. Flat-rate pricing offers simplicity by charging a consistent percentage or fee structure for many transactions, but the rate includes an embedded margin over underlying costs.
Comparing Pricing Models
Interchange-plus pricing separates the underlying interchange from an agreed processor markup, which can make pricing easier to analyze for merchants who understand their statements. Monthly platform fees, PCI-related services, chargeback fees, terminal rentals and optional software costs can change the real cost beyond the advertised transaction percentage.
Calculate Your Effective Rate
The effective processing rate is calculated by dividing total processing-related fees for the period by total card sales, while making sure one-time equipment or unrelated software charges are treated consistently. Businesses should compare pricing using their actual sales mix because a quote that is attractive for one merchant may not be the cheapest for another.
How to Make a Better Decision
When researching payment processing fees Canada how they work 2026, compare current rules, responsibilities, costs, timing, and risks that apply to your situation. For understand payment processing fees Canada, focus on reliable information and written terms. If you are considering credit card fees Canadian merchant 2026, keep useful records and ask questions before committing. With interchange vs markup payment Canada, compare options using the same criteria so the differences are easier to understand.
A useful approach is to review payment processing fees Canada how they work 2026 alongside understand payment processing fees Canada. Then check how credit card fees Canadian merchant 2026 affects the practical outcome and whether interchange vs markup payment Canada changes the decision. That broader comparison helps prevent decisions based on one headline, one price, or one assumption.
A Practical 2026 Checklist
Review current details before deciding. Write down the questions that still need answers. Check dates because requirements and pricing can change. Keep important records where you can find them later. Ask providers to explain unclear terms in plain language. Look beyond headline prices and consider total practical cost. Confirm who is responsible for each step of the process. Use the same criteria when comparing competing choices. Pay attention to exclusions, limits, deadlines, and special conditions. Think about how the decision works in everyday situations. Consider what could go wrong and how you would respond. Do not rely on a single advertisement or informal opinion. Reliable documentation is often more useful than confident sales language. Make sure your choice still works if circumstances change. A small amount of preparation can prevent expensive confusion later. Discuss complicated questions with a qualified professional when necessary. Recheck important assumptions before signing, paying, or making commitments. Your best option should match your goals, budget, and responsibilities. Good decisions usually come from clear information and careful comparison. Take notes during calls so promises and explanations are not forgotten. Ask whether fees, policies, or obligations continue after the first year. Read written terms before relying on what was said verbally.
FAQs
Q1: What are interchange fees and who sets them in Canada?
A: Interchange is part of the cost of accepting cards and is associated with payments to card issuers under card-network rules. The applicable rates depend on the network and transaction characteristics.
Q2: How does a payment processor mark up interchange fees for Canadian merchants?
A: A processor may add a percentage markup, per-transaction fee, monthly fee or other charges above underlying interchange and network costs, depending on the pricing agreement.
Q3: What is the difference between a flat-rate and interchange-plus pricing model?
A: Flat-rate pricing bundles costs into a simpler stated rate, while interchange-plus shows underlying interchange separately and adds the processor’s agreed markup.
Q4: How do I calculate my effective payment processing rate in Canada?
A: Add the processing fees you want to measure for the period, divide by total processed card sales and multiply by 100. Review what is included so comparisons between providers are consistent.